Cornerstone Home Lending Fund
Mortgage Debt
Real Homes. Real Equity. Real Collateral.
The Cornerstone Home Lending Fund is PPR’s flagship expression of the strategy the firm was built on. Since 2007, PPR has bought distressed mortgages secured by real home equity, loans the banking system has walked away from because they don’t fit inside a regulatory box. PPR scaled that strategy through its strategic operating partner starting in 2020, and the Cornerstone Home Lending Fund opens it to investors in a dedicated fund with shared upside.
The Strategy
Non-Performing Loan Strategy
The fund invests in residential mortgage debt, specifically first-position non-performing loans. It acquires a defaulted loan at a discount to what the home is worth, then works with the homeowner toward a resolution, most often a modification that gets them paying again. Because the loan sits in first position, the home’s value stands behind every dollar the fund commits, and the return comes from resolving the loan rather than from the payments it was supposed to make.
Investor Benefits
Downside Protection
Every loan is bought at a discount to the value of the home securing it.
A Proven Operator
Eighteen years of loan-level execution, now backed by institutional capital.
Keeping People in Their Homes
Resolution starts with modification, not foreclosure. Most resolved loans end with the homeowner current again or paid off.
Tap any benefit to expand
The Opportunity
Record Home Equity Behind Every Loan
Every loan the fund buys is secured by a residential property, and it’s purchased at a discount to that property’s value. That gap between purchase price and home value is the cushion. It’s what lets a defaulted loan get resolved without a forced sale. U.S. homeowner equity has grown from $27.4T to $34.1T since 2021 and now covers roughly 71% of total home value. That’s what makes the cushion possible.
How a non-performing loan resolves
Every path is a repayment event. The return comes from resolving the loan, not from the coupon.
Hover any stage for more detail. On a phone, tap it.
The collateral behind the thesis
Sources: Federal Reserve (Financial Accounts / Household Real Estate), industry data. Figures are approximate and for educational illustration.
The Thesis
Equity Matters More Than Credit
A low-LTV loan has historically lost very little, largely irrespective of the borrower’s credit. Loss risk is driven primarily by leverage, not credit score. The fund concentrates in the top-left corner of the grid, where the borrower’s equity cushion is deepest.
Gross lifetime loss rate by LTV × FICO. In a normal market, low-LTV loss is minimal across every credit tier — and it held in crisis.
FICO band (weaker credit ← left)
≤40% LTV × <580 FICO
Gross lifetime loss rate
Hover or tap any cell to see where its loss rate sits.
The Fund’s Corner: ≤40% LTV
Freddie Mac Single-Family Loan-Level Dataset: benign 2011–2016 and 2005–2008 crisis cohorts, through 2024; resolution mix at ≤40% LTV. Gross of MI. Low-FICO / ≤40% LTV cells rest on thin samples. For educational illustration.
How It Works
A Built-In Collateral Cushion
One principle runs through the whole strategy: buy well below what the home is worth. That margin is what makes a workout possible. When the fund’s basis sits far below the value of the house, there is room to modify a loan and keep someone in it rather than having to force a sale.
The Asset
First-Position Non-Performing Loans
A first-lien mortgage on which the borrower has stopped paying (90+ days). The fund acquires at a discount and creates value as each loan is resolved through modification, payoff, reperforming sale, or disposition.
Historic resolution paths (over 4,000 loans)
Past performance is not indicative of future results. These figures reflect the historical resolution of loan pools managed by PPR and are not a guarantee of future performance.
The Track Record
An 18-Year Record in Residential Debt
PPR Capital Management, formerly PPR Note Co, began as an acquirer and asset manager of non-performing loans in 2007 before transitioning into the institutional secondary mortgage market.
$2B+
Distressed residential debt acquired
$271M
Preferred returns earned through managed funds
11,000+
Individual loans resolved
$1.3B+*
Raised across 6 securitizations
Net Investor IRR by Fund
From inception through resolution or current fair value.
Our operating partner’s results across the six funds shown above. Data through December 31, 2025; PPR internal analysis for Fund 6 (mark-to-market). Past performance is not indicative of future results.
Every Discount Tier, Net Profitable
Loss frequency rises with price paid, but no tier has lost money on balance.
The Webinar
Go Deeper: The Full Briefing
Watch our team walk through the non-performing loan thesis and the Cornerstone Home Lending Fund in detail — where the mispricing comes from, how a defaulted loan resolves, and how returns are earned.
Case Studies
How Resolutions Play Out
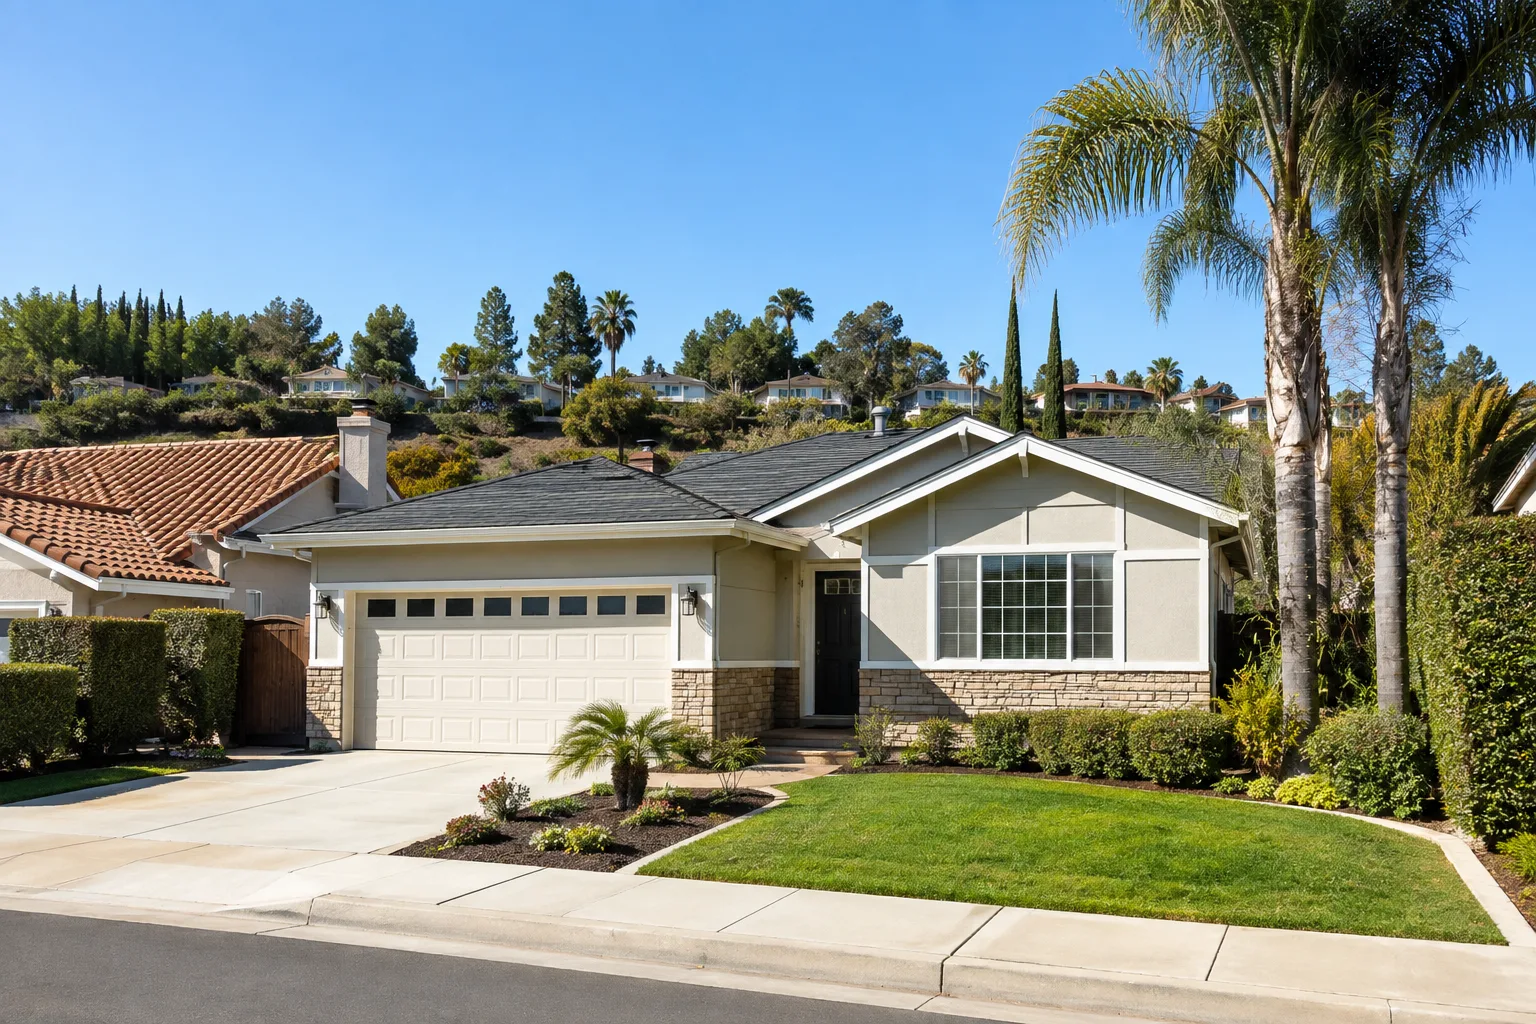
Real loans worked by PPR, from acquisition through exit. The property images are illustrative renderings rather than photographs of the homes themselves, to protect the privacy of the homeowners involved.
Case Study #1 · Loan Level
Location: California
Acquisition date
12/21/2023
Days to modification
211
Purchase price
$296,367
Property value
$850,000
Real loan worked by PPR. Property image is an illustrative rendering, to protect homeowner privacy. Individual results vary.
Value Breakdown at Liquidation
Bought and liquidated well below the home’s value — the blue band is the equity cushion above the fund’s basis.
Gross liquidation price
$376,870
Purchase Price + Gross Profit
Hover or tap a band on the bar to see how the deal breaks down.
Loan lifecycle
We leverage 18+ years and $2B+ in acquired residential debt to forecast a loan’s likely outcome — the resolution data that drives the price we pay to acquire it.
Acquired
12/21/2023
Modified
7/19/2024
RPL sold
4/16/2025
Total hold
482 days
Gross profit (loan level)
$80,502*
Annualized return
20.6%
Want to see how we underwrite?
Underwriting
Due Diligence on Every Loan
Before a pool is purchased, diligence reports are ordered on 100% of the loans, covering compliance, title, property, and legal status, so each loan is verified before a single dollar is committed. Every report independently confirms the collateral cushion the fund underwrites to, so nothing about a loan is taken on faith.
Tap any report to expand
Compliance Review
Confirms origination and servicing complied with applicable lending laws and regulations.
Servicing & Pay History
Verifies default status and payment behavior against the servicer's records and notes.
Tax & Title Search
Confirms property tax status and a clear, recordable chain of title.
Municipal Lien Search
Identifies unpaid municipal liens, such as code violations and utilities, attached to the property.
Exterior Property Inspection
An on-site drive-by confirms occupancy status and the physical condition of the property.
Broker Price Opinion
An independent local-broker valuation establishes the property's current market value.
Foreclosure & Bankruptcy Review
Local preferred counsel reviews the property's foreclosure and bankruptcy status and history.
Assignment-of-Mortgage Review
Confirms the assignment-of-mortgage chain is complete and properly recordable.
Initial Collateral Review
A first-pass review, via bailee, of the physical loan file and note held by the custodian.
*Loan-level gross profit, shown for demonstrative purposes only; it does not reflect financing costs or fund-level fees and expenses. The loan is real and was worked by PPR; the property image is an illustrative rendering, used to protect the homeowner’s privacy. Past performance is not indicative of future results.
Have Questions About the Cornerstone Home Lending Fund?
Talk it through with a PPR representative. No pressure, just answers.
Schedule a CallThe Free Ebook
What’s Inside The Shelter Effect
- Why residential real estate deserves a place in your portfolio
- The case for alternatives beyond stocks and bonds
- How private real estate earns income, growth, and tax efficiency
- What makes housing resilient through market cycles
- The risks to weigh, and how accredited investors get access
The Fund
Fund Terms at a Glance
A high-level summary of the Cornerstone Home Lending Fund. Complete terms, risks, fees, and conditions are set out in the fund’s Limited Partnership Agreement and offering documents, available to accredited investors on request.
Return Profile
12–14%+
Target Net Investor IRR
8%
Preferred Return
(Paid Current)
3 yrs
Fund Term
(After Initial Closing)
$50k
Investment Minimum
Fund
Cornerstone Home Lending Fund
Sponsor / GP
PPR Capital Management, LLC
Strategy
Residential Mortgage Debt: First-Position Non-Performing Loans
Target fund size
~$100M
Fund term
3 Years After Initial Closing
Investment period
1.5 Years
Preferred return hurdle
8% / Year
Target return, net of fees
12–14%+ IRR
Management fee
2.00% / Year on Unreturned Capital
Carried interest / promote
20% to GP After Return of Capital + 8% Preferred Return
Distributions
From liquidity events such as securitization, loan payments, payoffs, and property dispositions, at the manager’s discretion. Not guaranteed.
Reporting / K-1 timing
Quarterly + Annual Reports; K-1s
Investor eligibility
(Rule 501(a), Regulation D) who are also U.S. persons
Summary of key terms, subject to the Fund’s Limited Partnership Agreement and other governing documents. Target return and preferred return are forward-looking objectives, not guarantees or projections of actual results. This is not an offer to sell or a solicitation of an offer to buy any security. Investing involves risk, including possible loss of principal; past performance does not guarantee future results.
The Next Step
Ready to Evaluate the Fund Itself?
Review the confidential materials for the Cornerstone Home Lending Fund with our Investor Relations team: the offering documents, financials, and full track record.
- Private placement memorandum
- Fund financials and modeled returns
- Track record and case studies
Fund materials are intended for .